
AI Cash Flow Forecasting for Startups: How to Predict Runway, Burn, and Cash Needs
AI cash flow forecasting for startups helps founders and CFOs connect bank, accounting, payroll, billing, and revenue data to a continuously updated view of cash. It can reduce manual spreadsheet work, identify unusual transactions, explain variances, and test scenarios faster. It cannot fix incomplete data or replace financial judgment.
The most useful forecast answers three questions:
- How much cash does the company have?
- How quickly is it being consumed?
- What operating or financing decisions will change the outcome?
A static runway calculation may be enough for a quick estimate. A startup cash flow forecast is more useful because it models the timing of collections, payroll, vendor payments, taxes, debt, hiring, and fundraising.
New to financial operating systems? Start with our Financial Operating System 101 guide.
What is AI cash flow forecasting for startups?
AI cash flow forecasting combines connected financial data, deterministic cash calculations, statistical forecasting, machine learning, and management assumptions to estimate future inflows, outflows, cash balances, and runway. AI is most useful for classification, pattern detection, anomaly monitoring, variance explanations, and scenario analysis. The underlying financial arithmetic should remain transparent and reproducible.
Cash forecasting is not the same as profit forecasting. Profit can include non-cash items and accrual timing, while cash flow tracks when money actually enters or leaves the business. A company can report revenue and accounting profit while facing a cash shortfall because customers have not paid or major obligations are due.
The U.S. Small Business Administration recommends cash-flow projections as part of business planning. The Federal Reserve’s 2024 Small Business Credit Survey also documents the importance of financial conditions, revenue challenges, and access to capital for small businesses.
How is AI forecasting different from ordinary financial automation?
Traditional automation moves data, refreshes formulas, and reconciles records. AI-assisted forecasting adds interpretation: it can classify transactions, detect spending or collection changes, identify recurring patterns, summarize why a forecast moved, and compare alternative assumptions.
The distinction matters because automation can make a process faster without making it smarter. A reliable forecast still needs source-data controls, documented definitions, visible assumptions, calculation logic, and actual-versus-forecast review.
Why does cash flow forecasting matter for startup runway?
Cash flow forecasting matters because startups often combine volatile revenue, concentrated customers, long sales cycles, rapid hiring plans, and limited reserves. A rolling forecast connects those operating conditions to liquidity and shows when cash may fall below a defined operating reserve.
For solo founders, a forecast creates a repeatable weekly operating rhythm. For CFOs, it connects the operating plan with hiring, board reporting, fundraising, debt management, and risk controls.
How is runway calculated?
Runway is the estimated period before available cash falls to a defined minimum balance. The simplest formula is:
Runway in months = Available cash ÷ Average monthly net burn
For example, a company with $600,000 of cash and $60,000 of average monthly net burn has an approximate runway of 10 months.
That estimate can be misleading when collections, hiring, annual contracts, taxes, debt payments, or financing proceeds have unusual timing. A period-by-period cash forecast is more reliable because it shows the expected balance in each month.
Before building a rolling cash model, use the startup runway calculator to establish a baseline estimate.
Which runway scenarios should startups model?
Most startups should model at least three cases:
| Scenario | Purpose | Typical assumptions |
|---|---|---|
| Base case | Represents the most supportable operating plan | Current sales pipeline, planned hiring, expected collections, and committed expenses |
| Downside case | Tests resilience and action thresholds | Slower sales, delayed collections, higher costs, customer loss, or delayed fundraising |
| Upside case | Shows potential capacity without treating it as guaranteed cash | Faster growth, stronger retention, or earlier collections |
Runway should be measured against a minimum operating reserve, not only a cash-zero date. Waiting until the balance reaches zero leaves no room for execution delays, unexpected obligations, or financing risk.
How does an AI startup forecasting workflow work?
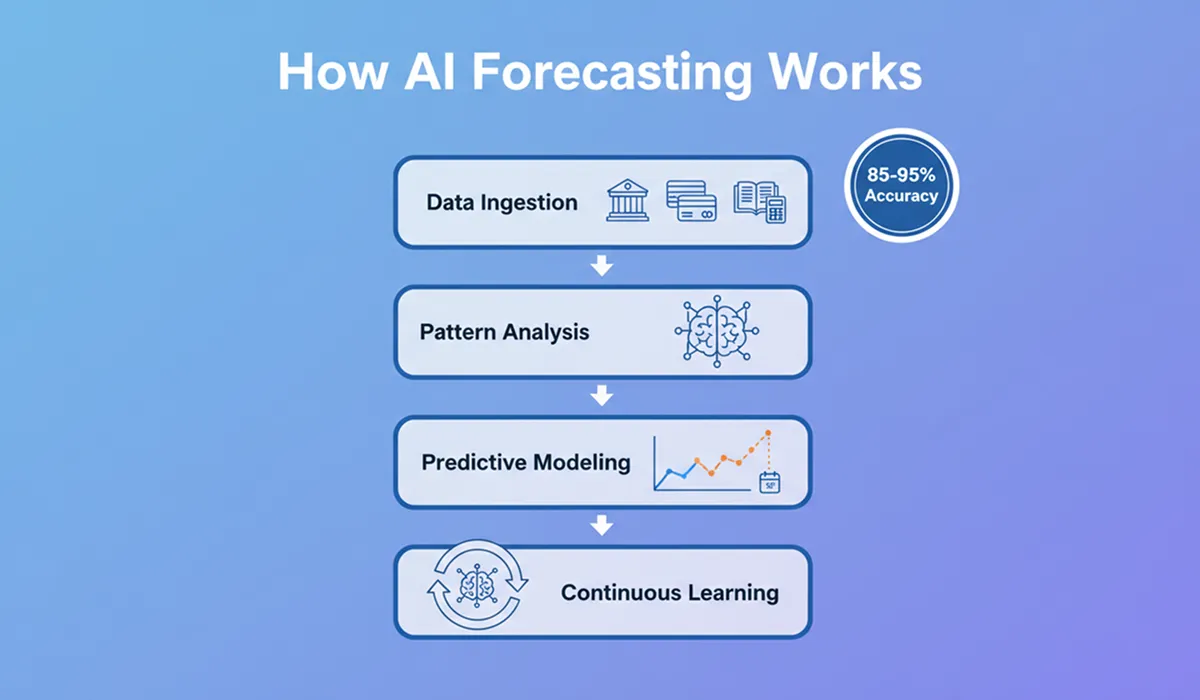
A dependable AI forecasting workflow has six stages: connect financial data, normalize transactions, add operating assumptions, calculate cash, compare scenarios, and review actual results. Software should handle repeatable calculations while AI assists with interpretation. Founders and CFOs remain responsible for assumptions, approvals, and decisions.
What data should a startup connect first?
Start with the sources that determine cash availability and near-term obligations:
- Bank accounts and credit cards.
- Accounting software such as QuickBooks or Xero.
- Payment processors such as Stripe or PayPal.
- Payroll and human resources systems.
- Billing, subscription, and customer relationship management tools.
- Debt, lease, and financing schedules.
For a solo founder, bank, accounting, payroll, and billing data are usually the best starting point. A CFO may also need permissions, audit history, board-reporting data, and multiple operating entities.
Connected data is useful only when it is mapped consistently. Duplicate records, missing payment dates, uncategorized expenses, and inconsistent revenue definitions can distort a forecast regardless of the model’s sophistication.
How should financial data be normalized?
Normalization converts raw transactions into consistent categories and periods. It can separate recurring revenue from one-time revenue, classify payroll correctly, identify intercompany transfers, and distinguish cash timing from accounting recognition.
Document the following before relying on forecast outputs:
- Revenue categories and recognition rules.
- Fixed, variable, step, discretionary, and one-time expenses.
- Recurring versus non-recurring costs.
- Accounts receivable and accounts payable timing.
- Planned hires and contract changes.
- Debt, tax, and financing obligations.
- Unusual or non-operating transactions.
A forecast that changes definitions from month to month may appear precise while becoming less useful for trend analysis.
Which assumptions should management add?
Historical data cannot represent every future event. Management must add known changes such as a planned hire, contract renewal, price increase, tax payment, office move, debt repayment, or fundraising event.
Useful assumptions include:
- Headcount and start dates.
- Salary, benefits, payroll taxes, and recruiting costs.
- Customer acquisition and conversion.
- Churn, renewal, and expansion.
- Invoice terms and collection timing.
- Vendor contracts and payment schedules.
- Hosting, fulfillment, and payment-processing costs.
- Financing proceeds and repayment terms.
AI can suggest patterns from historical data, but it should not silently invent assumptions.
How should a forecast use AI?
AI can assist with transaction categorization, anomaly detection, recurring-payment identification, collection-pattern analysis, variance explanations, and natural-language questions about the model.
The financial system should use deterministic logic for balances, formulas, and cash schedules. An AI model may summarize a verified forecast, but it should not be the system of record for financial arithmetic.
Which startup metrics should a cash forecast monitor?
A useful startup forecast combines cash metrics with operating drivers. Cash shows when liquidity may become constrained; operating metrics explain why. The right set depends on the company’s business model, billing terms, sales cycle, headcount plan, and financing structure.
What should a startup cash flow forecast include?
At minimum, include the following:
- Opening cash balance.
- Expected collections.
- Payroll and benefits.
- Vendor and operating payments.
- Taxes.
- Debt and lease payments.
- Financing proceeds.
- Closing cash balance.
- Minimum operating reserve.
- Runway and cash-zero date by scenario.
The model should distinguish bookings, billings, recognized revenue, and collected cash. For invoice-based businesses, collections may matter more to near-term liquidity than bookings. For subscription businesses, failed payments, renewal timing, churn, expansion, and payment terms can materially affect cash.
How should founders measure burn?
Gross burn is total cash spending during a period. Net burn is cash spending minus cash generated from operations. Both metrics help management understand liquidity:
- Gross burn: The total scale of cash spending.
- Net burn: The rate at which operating cash is being consumed.
- Burn trend: Whether spending is accelerating or slowing.
- Burn multiple: The relationship between net burn and net new recurring revenue.
Common formulas are:
Net burn = Cash operating expenses − Cash operating inflows
Burn multiple = Net burn ÷ Net new recurring revenue
A single month can be distorted by annual contracts, hiring cycles, delayed collections, or one-time expenses. Compare current results with a trailing average and investigate material changes.
Which revenue metrics should be forecast?
Revenue and cash forecasts may include:
- Monthly recurring revenue.
- Annual recurring revenue.
- New customer acquisition.
- Conversion rate.
- Average revenue per customer.
- Expansion and contraction.
- Churn and retention.
- Bookings, billings, and collections.
These measures are not interchangeable. ARR is a run-rate measure, recognized revenue follows accounting rules, and collections depend on invoices, payment terms, and customer behavior. A sound model reconciles pipeline to bookings, billings, recognized revenue, and collected cash.
How should startup expenses be modeled?
Expenses should reflect their economic behavior:
| Expense type | Examples | Forecasting approach |
|---|---|---|
| Fixed | Base salaries, rent, core software | Model as recurring commitments |
| Variable | Payment processing, hosting, fulfillment | Tie to revenue, usage, or transaction volume |
| Step cost | Additional support capacity or infrastructure | Add when a capacity threshold is reached |
| Discretionary | Travel, outside services, marketing programs | Model as controllable commitments |
| One-time | Legal work, equipment, implementation | Enter in the period when cash is expected to leave |
AI can identify recurring patterns, but management must enter known future changes and decide which expenses are controllable.
How does a worked forecast change a startup decision?
A worked example shows why period-by-period cash forecasting is more useful than dividing cash by average burn. Consider a hypothetical startup with $600,000 of cash, $100,000 of monthly gross burn, and $40,000 of monthly collections. Its initial net burn is $60,000, implying approximately 10 months of runway.
Now assume three changes:
- A $100,000 customer payment is delayed by one month.
- The company hires an employee whose fully loaded monthly cost is $15,000.
- A planned financing closes two months later than expected.
The revised cash impact is more important than the average-burn formula:
| Period | Base closing cash | Downside closing cash | Main difference |
|---|---|---|---|
| Starting balance | $600,000 | $600,000 | Same opening cash |
| Month 1 | $540,000 | $525,000 | New hire begins; downside collections are delayed |
| Month 2 | $480,000 | $365,000 | Delayed $100,000 payment remains outstanding |
| Month 3 | $420,000 | $300,000 | Higher burn continues; financing is delayed |
| Month 4 | $360,000 | $240,000 | Downside runway reaches the action zone sooner |
The exact result depends on payroll timing, tax treatment, collection dates, and financing terms. The decision insight is clear: average burn can hide a timing problem. A founder might approve the hire under a 10-month average-runway view but defer it after seeing that downside cash falls below the operating reserve several months earlier.
A CFO can use the same model to define an action trigger, such as delaying the hire, accelerating collections, reducing discretionary spend, or beginning fundraising earlier.
How can AI improve financial planning and decision-making?
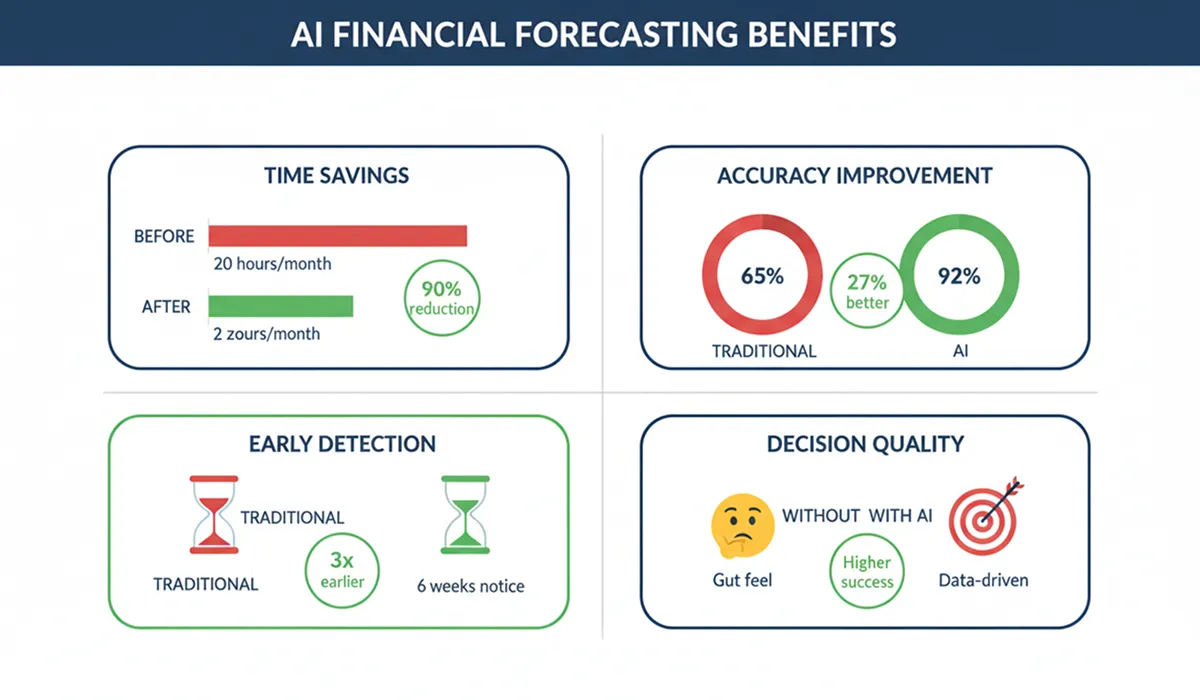
AI is most valuable when it gives management time to act. It can surface slower collections, rising infrastructure costs, unexpected vendor spend, or a hiring plan that materially shortens downside runway.
How can AI detect financial problems earlier?
An AI-assisted system can flag changes such as:
- Collections falling below the expected trend.
- Vendor spending exceeding a category threshold.
- Payroll increasing faster than the hiring plan.
- Customer churn changing materially.
- Payment-processing fees rising.
- Projected cash falling below a reserve threshold.
Alerts should be actionable. Each one needs an owner, a threshold, and an expected response. Too many low-value alerts create noise and may cause the team to ignore important warnings.
How can forecasting improve hiring decisions?
Hiring should be modeled as a total cash commitment, not only annual salary. Include wages, payroll taxes, benefits, recruiting costs, equipment, commissions, and the delay before the employee contributes revenue or productivity.
A forecast can compare hiring now, hiring later, using a contractor, or setting a revenue-based hiring trigger. It informs the financial trade-off but does not make the cultural, product, or strategic judgment for the leadership team.
How can forecasting support fundraising?
A fundraising forecast shows how much capital the company needs, when it needs it, and which milestones the financing is expected to fund. It should include:
- Opening cash and committed financing.
- Monthly revenue and collection assumptions.
- Headcount and operating expense plans.
- Gross and net burn.
- Base, downside, and upside scenarios.
- Monthly cash balance and runway.
- Milestones associated with the next financing.
- Repayment, conversion, or other relevant financing terms.
The National Venture Capital Association’s model legal documents illustrate why financing terms can create obligations that affect cash planning. Fundraising should therefore be modeled as a financing event with conditions and assumptions, not simply as free cash.
How can AI support pricing and unit economics?
Pricing analysis should connect price changes with conversion, churn, expansion, gross margin, and collection timing. A higher price may increase revenue per customer while reducing conversion or increasing churn.
Useful metrics include:
- Customer acquisition cost.
- Gross margin.
- Contribution margin.
- Payback period.
- Retention and churn.
- Lifetime value under defined assumptions.
David Skok’s SaaS Metrics 2.0 framework provides a widely referenced framework for analyzing SaaS economics. Its metrics are analytical tools, not universal targets for every startup.
Which forecasting approach fits each startup stage?
The right forecasting method depends on the company’s data history, business model, transaction complexity, and decision needs. AI adds the most value when the company has consistent data and recurring decisions. Driver-based modeling is usually more appropriate when history is limited or the business is changing rapidly.
| Startup situation | Recommended approach | Why |
|---|---|---|
| Pre-revenue startup | Driver-based cash model | There is little historical revenue data; assumptions about hiring, expenses, and financing matter most |
| Early-revenue startup | Weekly cash forecast with scenarios | Collections and customer timing are becoming measurable but may remain volatile |
| SaaS company with recurring billing | Cohort, retention, billing, and collection model | Churn, renewals, expansion, failed payments, and payment terms affect cash |
| Agency or services business | Pipeline, utilization, invoicing, and collections model | Revenue depends on projects, staffing capacity, milestones, and customer payment behavior |
| Venture-backed company preparing to raise | Integrated operating and financing model | Investors need a clear connection between capital, milestones, hiring, growth, and runway |
A company does not need a complex predictive model to make better decisions. A transparent weekly cash schedule with documented assumptions is often more valuable than an opaque model with sophisticated terminology.
How should a startup implement AI forecasting?
Implementation should be treated as a controlled finance process rather than a one-time software installation. Start with reliable data, establish a baseline, validate outputs, and add complexity only when it improves decisions.
What should happen during the first week?
During the first week:
- Connect the primary bank and accounting systems.
- Import sufficient historical data for the business model.
- Map revenue and expense categories.
- Identify recurring payments and known commitments.
- Define the minimum cash reserve and runway thresholds.
- Review the first forecast against bank and accounting balances.
The objective is not to build a perfect three-year model immediately. It is to establish a baseline that management can inspect and improve.
What should happen during the first month?
During the first month:
- Add payroll, billing, and payment-processor data where useful.
- Record planned hires, contract changes, taxes, debt, and financing.
- Build base, downside, and upside scenarios.
- Compare forecast values with actual cash weekly.
- Review operating metrics monthly.
- Document material assumption changes.
- Assign owners to emerging risks and actions.
Resolve data issues before tuning the model. More integrations do not automatically create better forecasts.
How often should founders and CFOs review the forecast?
A weekly cash review is appropriate for companies with limited runway, volatile collections, or major upcoming commitments. A monthly full-model review is usually sufficient for operating assumptions, metrics, and board reporting.
A solo founder may need a concise weekly view of cash, collections, payroll, and runway. A CFO should also define who can change assumptions, how changes are documented, and when a forecast version is locked for reporting.
What should a weekly forecast review checklist include?
Use this checklist for each weekly review:
- Is the actual bank balance reconciled?
- Did collections arrive when expected?
- Are payroll and vendor commitments covered?
- Did gross or net burn change materially?
- Did any customer, vendor, or payment term change?
- Is downside runway below the action threshold?
- Which forecast assumptions were wrong?
- What action has an owner and deadline?
- Which changes should be carried into the next forecast version?
How should you choose an AI financial forecasting tool?
Choose a tool based on data reliability, transparency, workflow fit, security, and total cost—not on the most impressive AI label. Solo founders may prioritize speed and plain-language explanations. CFOs may need permissions, auditability, scenario controls, version history, and board-ready reporting.
Which forecasting features matter most?
Look for:
- Bank and accounting integrations.
- Payment, payroll, and billing connections.
- Transparent assumptions and calculations.
- Cash, burn, runway, and scenario views.
- Actual-versus-forecast variance analysis.
- Exportable reports.
- Role-based access and audit history.
- Documented manual overrides.
- Clear data-retention and security policies.
- A trial or low-cost entry plan.
A product should make it easy to answer not only “What is the forecast?” but also “Why did it change?” and “What action should we consider?”
What are warning signs in an AI forecasting product?
Be cautious if a product:
- Promises guaranteed forecast accuracy.
- Cannot explain its calculations.
- Treats an LLM response as the financial model.
- Requires extensive manual data entry.
- Provides no actual-versus-forecast reporting.
- Hides integration limits or implementation costs.
- Has unclear security or data-retention practices.
- Does not allow management to document assumptions.
How does Uniflow compare with other startup finance approaches?
Uniflow is an AI-powered financial operating system for startups that centralizes financial visibility, supports cash and runway planning, and helps founders and finance teams maintain a repeatable forecasting workflow. It is designed for teams that want more than a static spreadsheet while keeping management responsible for assumptions, approvals, and decisions.
Uniflow fits between disconnected financial tools and more complex planning processes. A startup can use it to organize the recurring workflow around financial data, cash visibility, runway monitoring, scenario review, and management action. The appropriate level of automation still depends on data quality and company complexity.
| Approach | Best for | Strengths | Trade-offs |
|---|---|---|---|
| Uniflow | Solo founders and startup finance teams | Centralized financial visibility, cash and runway planning, AI-assisted insights, and a repeatable operating workflow | Requires reliable connected data and an implementation process |
| Spreadsheet model | Companies with simple structures or highly customized requirements | Flexible, familiar, and easy to modify | Manual updates, version-control risk, and limited monitoring |
| Accounting software alone | Basic bookkeeping and historical reporting | Useful source of record for transactions and accounts | Usually requires additional modeling for runway and scenarios |
| Fractional CFO or FP&A support | Teams needing judgment, planning, and investor support | Strategic context and customized analysis | Higher cost and less automation for recurring data work |
| Dedicated forecasting platform | Finance teams with complex planning needs | More advanced planning, reporting, and scenario capabilities | May require more setup, training, and budget |
For solo founders, the transition point usually occurs when maintaining the spreadsheet takes more time than reviewing decisions. For CFOs, it occurs when data lineage, permissions, version control, and repeatable variance review become operating requirements.
What are the limitations of AI financial forecasting?
AI forecasting is not a substitute for accounting controls, a CFO, or management judgment. Its output is only as reliable as the underlying transactions, definitions, assumptions, and forecast horizon. It is weakest when a company is new, changing its business model, or facing an event with no relevant historical pattern.
Can AI calculate runway reliably?
A financial forecasting system should use deterministic software for arithmetic, balances, and formula-based calculations. Large language models generate probable text; they should not serve as the system of record for financial arithmetic.
The NIST AI Risk Management Framework emphasizes validity, reliability, transparency, and accountability in AI systems. In financial workflows, that means exposing source data, calculation logic, assumptions, and exceptions rather than returning an unexplained number.
AI can summarize a verified forecast and identify patterns. It should not invent missing data or independently approve a high-impact financial decision.
How much historical data does a startup need?
Three to six months of consistent data can support an initial operating forecast, but 12 months or more is generally more useful for businesses with seasonal patterns. A new product or recently changed business model may have no relevant historical cohort.
When history is limited:
- Use driver-based assumptions.
- Label assumptions clearly.
- Apply conservative ranges.
- Use industry benchmarks cautiously.
- Review actuals frequently.
- Avoid presenting point estimates as reliable predictions.
Can AI predict a pivot or black swan event?
AI cannot reliably predict an unprecedented market shock, regulatory change, major pivot, or sudden customer-concentration event from historical data alone. It can quantify manually defined stress scenarios, but management must supply the scenario and assess its strategic plausibility.
Useful stress tests include:
- Revenue declines of 30%, 50%, or 70%.
- Collections delayed by 30 or 60 days.
- Loss of a major customer.
- Infrastructure costs doubling.
- Fundraising delayed by six months.
- An immediate hiring freeze.
When is manual forecasting better?
Manual or driver-based forecasting may be better when the company is pre-revenue, has little historical data, is changing its business model, or needs to model a decision with no historical precedent. AI becomes more useful as transaction history, customer behavior, and operating definitions become consistent.
The strongest process is hybrid:
- Software handles synchronization and repeatable calculations.
- AI identifies patterns, summarizes variances, and proposes questions.
- Founders and CFOs set assumptions and interpret strategic context.
- Finance leaders approve the final plan and actions.
“All models are wrong, but some are useful.” — George E. P. Box, Science and Statistics (1976), American Statistical Association
The objective is not perfect prediction. It is a transparent model that improves decisions under uncertainty.
How should startups measure forecast quality?
Forecast quality should be measured by error, explainability, and decision usefulness—not by a vendor’s unsupported accuracy percentage. Review performance by metric and time horizon because a forecast may be useful for weekly cash while remaining uncertain for twelve-month revenue.
| Measure | Formula or method | What it reveals |
|---|---|---|
| Cash balance variance | Actual closing cash − forecast closing cash | Whether the cash schedule is tracking reality |
| Collections variance | Actual collections − forecast collections | Whether customer payment assumptions are reliable |
| Burn variance | Actual net burn − forecast net burn | Whether spending or operating inflows changed |
| Cash-zero-date variance | Actual or revised date − prior forecast date | Whether runway moved materially |
| Forecast error by horizon | Compare one-week, one-month, and three-month forecasts with actuals | How quickly forecast reliability declines |
| Variance by category | Compare payroll, vendors, taxes, and other major categories separately | Which assumptions need attention |
Do not change assumptions merely to make a forecast appear accurate. Record whether a variance came from a data error, timing difference, faulty assumption, or genuine business change.
What are the best practices for AI cash flow forecasting?
The core practices are to maintain clean source data, separate actuals from assumptions, use explicit scenarios, review variances regularly, and keep humans accountable for decisions. Treat the forecast as a decision system rather than a static report.
How should startups improve financial data quality?
Startups should:
- Reconcile bank and accounting balances.
- Remove duplicate transactions.
- Categorize expenses consistently.
- Separate operating and financing cash flows.
- Confirm invoice and payment dates.
- Record committed contracts and obligations.
- Document changes to revenue definitions.
- Lock reporting periods after review.
Automation can process bad data faster, but it cannot turn an incorrect transaction classification into a correct forecast.
Why should startups use scenarios?
Scenarios show which variables matter most and give management predefined responses. At minimum, model changes to revenue growth, churn, collections, hiring, gross margin, and fundraising timing.
Use scenarios to answer specific questions:
- Can we hire while preserving 12 months of downside runway?
- What happens if collections slow by 45 days?
- How much capital is required if growth is delayed?
- Which expenses can be reduced without impairing core operations?
- What trigger would cause management to change course?
How should founders and CFOs divide responsibilities?
A practical division of responsibility is:
- Software: Synchronize data, calculate balances, and preserve forecast versions.
- AI: Identify patterns, draft explanations, and highlight anomalies.
- Founder or CFO: Approve definitions, assumptions, thresholds, and actions.
- Accounting and finance team: Reconcile actuals and investigate material variances.
- Leadership: Decide on hiring, spending, pricing, fundraising, and risk response.
This division preserves speed without confusing analysis with accountability.
What is the conclusion about AI cash flow forecasting for startups?
AI cash flow forecasting gives founders and CFOs faster visibility into runway, burn, collections, expenses, and strategic trade-offs. Its value comes from reducing repetitive work and improving the speed of analysis—not from guaranteeing a correct prediction.
A practical adoption plan is:
- Establish a clean cash baseline.
- Connect the most important financial sources.
- Define revenue, expense, collection, and runway assumptions.
- Build base, downside, and upside scenarios.
- Compare forecasts with actuals every week or month.
- Measure forecast error by category and time horizon.
- Use AI for pattern detection and explanations.
- Keep humans responsible for financial decisions.
Uniflow provides an AI-powered financial operating system for organizing startup financial data, supporting cash visibility, and maintaining an ongoing forecasting workflow. Explore the Uniflow financial operating system or establish a baseline with the startup runway calculator.
Which related articles should you read next?
- Financial Operating System 101: Complete Guide
- Uniflow vs. Spreadsheets: Why Make the Switch
- Financial OS vs. Traditional FP&A
- Why Founders Fail at Financial Planning
What are the frequently asked questions about AI financial forecasting?
How accurate is AI cash flow forecasting?
Accuracy varies with data quality, forecast horizon, business maturity, seasonality, and model design. A stable company with consistent transaction history can forecast more reliably than a pre-revenue startup or a company undergoing a pivot. Evaluate tools using back-testing, variance reporting, transparent assumptions, and confidence ranges.
How much historical data does a startup need?
Three to six months of consistent data can support an initial operating forecast, while 12 months or more is more useful for seasonal businesses. Startups with less history should use driver-based assumptions, conservative ranges, and frequent actual-versus-forecast reviews.
Do founders need finance or data science expertise?
Founders do not need data science expertise, but they need enough financial understanding to define categories, validate assumptions, and interpret results. AI can automate data handling and explain variances in plain language. It should not replace accounting controls or professional advice involving tax, debt, securities, or legal obligations.
Can AI forecast revenue for a SaaS startup?
AI can estimate revenue using pipeline, conversion, expansion, churn, customer cohorts, billing terms, and collections. Forecast quality depends on consistent definitions. ARR, MRR, bookings, billings, recognized revenue, and cash collected are different measures and require a clear reconciliation.
Can AI predict a startup’s cash-zero date?
AI can estimate a cash-zero date by combining opening cash, expected inflows, expenses, financing, and timing assumptions. The result is a range rather than a certainty. Founders should review the date under base and downside scenarios and maintain a minimum operating reserve above the modeled zero balance.
Will AI forecasting replace a CFO?
AI is more likely to automate recurring data work and improve CFO productivity than eliminate the need for financial leadership. CFOs provide judgment on strategy, capital allocation, fundraising, controls, risk, and investor communication. AI can prepare analysis, but leadership remains accountable for decisions.
How much does AI financial forecasting cost?
Pricing depends on the product, integrations, users, data volume, and support level. Some tools offer free or low-cost entry plans, while paid software and fractional finance support can range from modest subscriptions to substantially higher custom fees. Confirm current pricing, integration limits, implementation costs, and contract terms directly with each provider.
Is financial data secure in an AI forecasting tool?
Security depends on the provider’s architecture and controls. Before connecting accounts, review encryption practices, access controls, data retention, subprocessors, incident response, authentication, and available independent certifications or audits. An AI label alone does not establish bank-level security or regulatory compliance.
Can AI forecast a black swan event?
No. AI can model a manually defined stress scenario, but it cannot reliably predict an unprecedented event from historical data. Use downside planning, cash reserves, financing contingencies, and explicit stress tests for events such as major customer loss, market disruption, regulatory change, or delayed fundraising.
About the Author: Michael Stan is an accountant, financial advisor, and founder of Uniflow. He has spent more than a decade advising early-stage startups and building financial systems that help founders understand cash flow, runway, and growth decisions.